No it maxes out at 23.8%
1 Like
well I’m going by this:
Long-term capital gains tax rates for the 2021 tax year
| FILING STATUS | 0% RATE | 15% RATE | 20% RATE |
|---|---|---|---|
| Single | Up to $40,400 | $40,401 – $445,850 | Over $445,850 |
| Married filing jointly | Up to $80,800 | $80,801 – $501,600 | Over $501,600 |
| Married filing separately | Up to $40,400 | $40,401 – $250,800 | Over $250,800 |
| Head of household | Up to $54,100 | $54,101 – $473,750 | Over $473,750 |
Source: Internal Revenue Service
Research IRS form 8960, including who has to include it in their returns, and what the tax is. It throws an extra 3.8% tax on top of that.
OK so the technical detail is that the tax I’m talking about is NOT called the Long-Term capital Gains tax. It is the 3.8% Medicare contribution tax. It certainly IS assessed on long term capital gains (and other investment incomes), at least for some people. But it is assessed on people who earn a lot less than 450k, not only those who earn 450k or more.
So while the LTGC Tax is 0% or 15% or 20% as you describe, the total tax assessed against LTCGs might be 0%, 15%, or 18.8% or 23.8%. I don’t think it can be exactly 20% because if you earn enough to pay the 20% tax you are most assuredly also paying the extra 3.8%.
Read line 17 here:
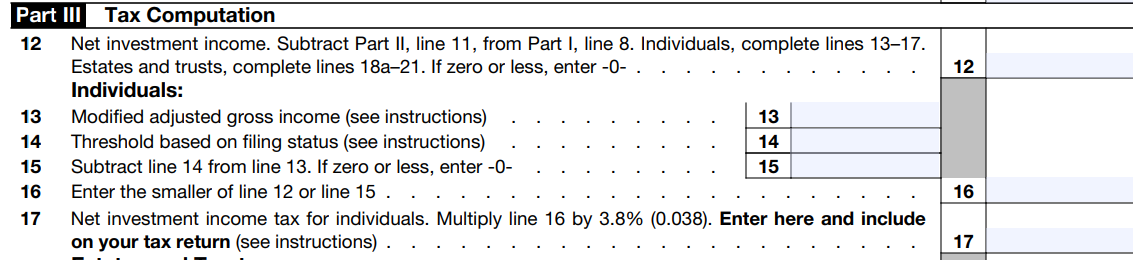
2 Likes
I don’t get too many ballers at VITA, but I do get a few since you have to be low income OR elderly. And yep, Deep Purple is spot on here.
Still, 23.8% may well be under your marginal tax rate for short term gains. And since those are, of course, are ALSO subject to the 3.8% NIIT… simply comparing the 20% rate to your marginal tax rate will give you an idea of the difference.
But yeah, technically you should be comparing 23.8% to marginal rate plus 3.8%. If you’re subtracting it obviously doesn’t matter. If you’re dividing, it’s got a small impact.
I’m not an expert so you’re probably right. I was going off a quick read on a website that seemed legit, maybe I misinterpreted, maybe they’re wrong. Seems you are likely more informed/accurate.
I’m back in SPY and ARKK till I see a dip
Got some F 3/16 $25 Calls too
Still holding onto my 12/17/21 VRT $25 Calls

1-year RoR of 45.3%. I heard Biden was going to crash the economy? In 11/2020 alone I gained 13%. Just in mutual funds/overall market indices.
Peleton (PTON) eating shit sandwiches today
about a year ago I made a big bet on SPY with the thought that Trump would win the election and the market would go nuts.
Turned out to be a great move, but for the wrong reasons. Ill take the 42% return on it (SPY dipped to the 320’s the week of the election). I like to use this as an example of my ‘i dont know shit’ philosophy in investing that has lead to mostly DCA as I age.
All I really do now is stock some cash, wait for a dip, then buy more SPY. repeat.
Same. I played some of the WSB things, and bought some DAL and NCLH stock when Covid cratered everything. And I own some crypto. But these are all on the order of 0.1% of my portfolio. By and large, I buy and hold, and if there’s a big dip, then I dig under the couch cushions to buy even more. That worked well during Covid, my travel costs went to zero so I had a bit of room in the budget to buy more equities.
If I really thought I could beat the market, I’d be doing that for a living.
If you want to gamble, just download draftkings. its way more fun betting on sports vs stocks.
1 Like
Well, my portfolio not doing well today
anyone taking a chance on RIVN?
i tried to buy at the IPO 78, but it’s at 112 now and still climbing
nah right now EV stocks are all overvalued in my books
I will reconsider if I ever buy an EV
Except Nio!
Yeah, RIVN is higher market cap than most 100+ year automakers. not 5 years ago did I think this was possible
it’s not a sucker bet if u win
You can only win big if you don’t think like the mass
u mean like shorting tesla?
smart money doesn’t work in this market
is that what the mass thinks?