I’m not chasing it, although I have gone for a few roles internally that would have been a move up.
1 Like
Yes, if you think you’ve reached the $ goal you are looking for, you don’t really need the 10k.. Besides sticking around doesnt help because you will vest some options and gain more unvested ones.
JUST SAY NO to one more year!
2 Likes
Trying really hard. I really think my company will IPO next year, once I see the number on that I’m going to evaluate things. If the valuation holds then I’m going to try to convince my wife to quit her job and find something lower stress. We would be at or very near the number, barring a recession. I’d be looking to stick around about a year or so and I think we’d be golden.
2 Likes
The IPO you said was much more significant money. Your retirement is somewhat tied to an IPO, how bizarre how bizarre. The wheels in your head will do some serious turning once that starts…
It’s obviously hard to pin down, prices on a single stock can move around. It’s likely to be in the half million range, it’s not the only thing but it’s an important thing.
The last few bits that may keep me working just a bit longer are funding a few key things. My wife’s car is 13 years old, she doesn’t want a new car but I’d like to put aside funds for that. As well as pre-funding the last of the home renovations, which is down to about $40k or so. Just so that when we do pull the plug, the odds of needing something $$$ out of the gate is low. I’m probably forgetting some things, I might want an extra $100k just to kick things off an a high note. If the IPO goes well I think we’d be within a quarter million of that.
1 Like
some companies may have a distinction between resigning (quitting and going to work elsewhere) and retiring (ending a career). So retirees may still eventually collect the outstanding deferrals in accordance with the vesting schedule
1 Like
At my big company I think to officially make “retirement” status you needed a combination of years of service and age to vest remaining options. 52+9=61 certainly didn’t cut it.
2 Likes
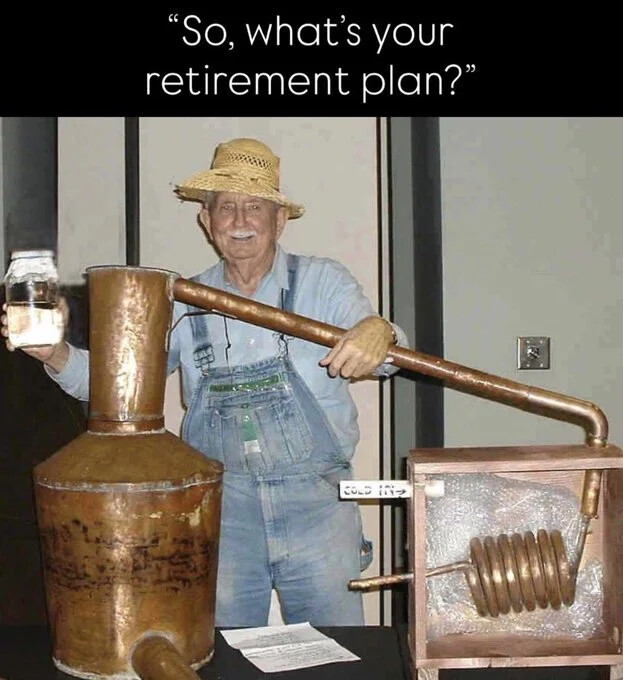
Funny, one of the hobbies high up my list to start when I retire is brewing beer.
1 Like
I set up a still in my rooming house when I was in university. Not sure what the final product was but it burned on the way down.
3 Likes
For a moment there I thought you were talking about the rooming house.
3 Likes
The rooming house should have been burned down!
My room only cost $8 per week.
3 Likes
My wife reviewed, and approved, my budgets. I’ve built three options. There is a ‘leanFIRE’ version, which honestly isn’t all that lean, and we are at 99.8% of that number. So if one of us gets fired tomorrow, probably gonna be ok. Then I put together what I think we want to have in life going forward, the base case, at 4% withdrawals. The last scenario I cooked up using 4.5% withdrawals and some really fat numbers for things like travel. I was thinking we could start there at a 4.5% withdrawal and obviously have room to trim expenses if the markets demand it. Anywho, that number came out almost exactly equal to what we’d need for scenario two. We are at 90% for those scenarios.
That does not include paying off the house, pre-funding the last of the home renovations, and pre-funding a car for my wife, and buying an Eames lounge chair, lol. All in, I need almost exactly a half million and I think we’re pretty much done. Maybe I’m still forgetting something but I think I’m pretty close.
Beyond that, we’ve discussed working a bit more to take a long around-the-world vacation. Maybe. Other than that, we have everything we need and probably 95% of what we want. I suppose if work isn’t too bad I could do a lot of good for others with my actudonk salary for 6-12 months.
3 Likes
I’m glad to hear you have your Sheet together!!! 
3 Likes
you folks talking about retirement and I’m over here in the corner having a crisis over not having enough time to do everything that Id like to do.
1 Like
Math Challenge
I invite you to:
- Do some calculations.
- Post your thoughts. Please hide the details so that others can post their calculations before reading/being influenced by other’s people ideas,
Picking a nice round number: $10,000. How much would make you comfortable to have $10,000 per month (net of taxes with likely vary by state) for a long retirement, with inflationary adjustments as you desire and plan for, and without regards to any other income stream like SS.
I guess you should probably state some sort of assumption on a general category of asset mix and planned returns.
I’ll admit, I’ve read lots of articles on safe WD rates over the years, and while they are compelling, I usually come back to the 4% rule, I guess now it’s the 4.5% rule. So I just take $120k/year divided by one plus the tax rate, that’s the annual income. Divide by 4% or 4.5% and I’m done. And then for me, add $100k for pre-funding some stuff.
That’s low risk even on a 30Y horizon w/o SS, and if I retire today I’m 19 years from FRA so that adds another buffer.
I think you mean (1 - tax rate%) not 1 PLUS the percentage, right? So by my math your answer is 3,333,000 or so assuming a 20% tax rate
1 Like
Math is hard. Wait, that number assumes 10% tax, not 20%?
1 Like
Here:
Summary
3,333,333 = 10,000 * 12 / (1-.2) / .045
Gross Amt = Monthly Requirement * 12mo/yr / Net Post Tax Retention / Withdrawal Rate